Create Balanced QuickBooks Journal Entries With Confidence
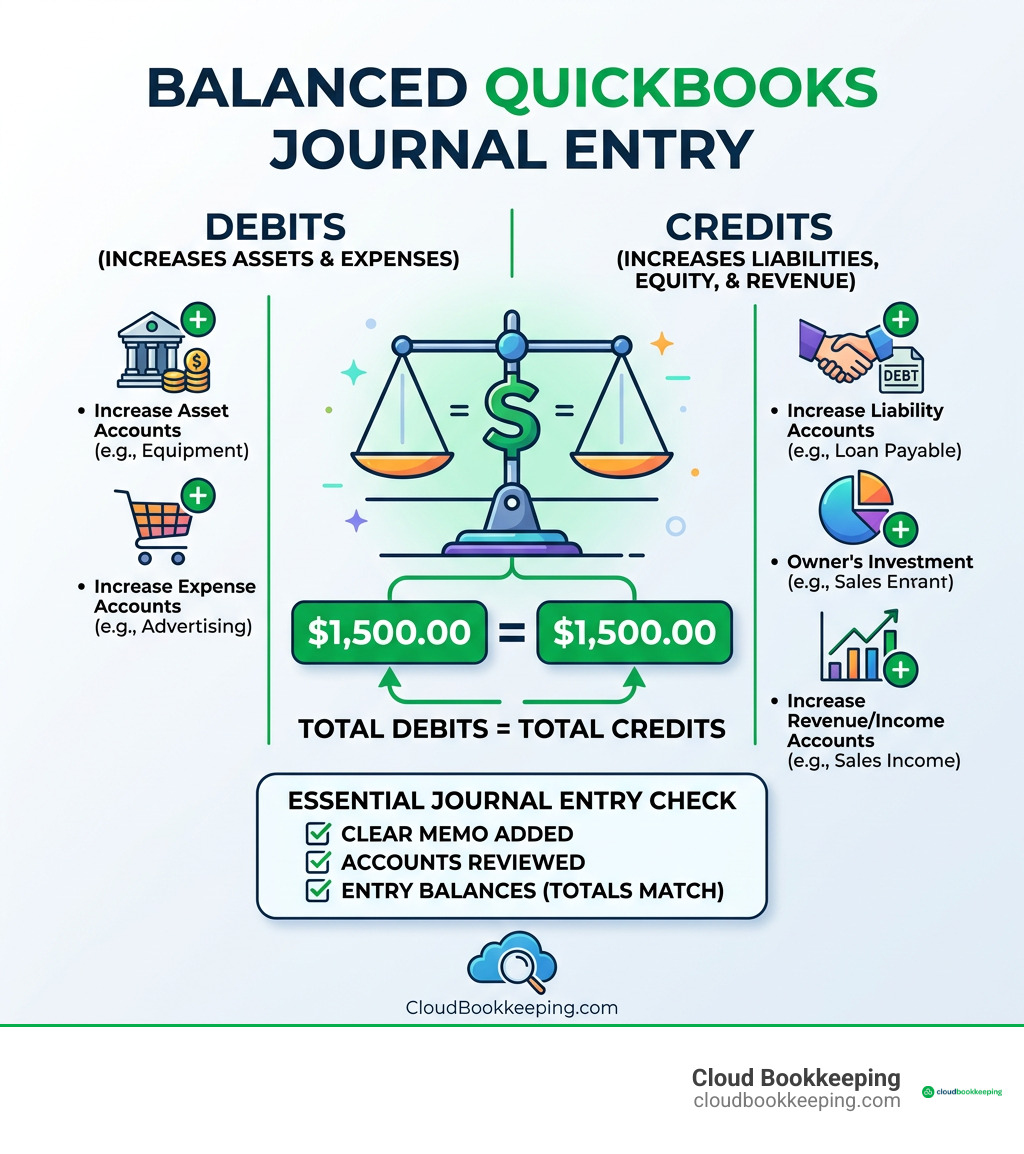
To create a balanced journal entry in QuickBooks, choose the Journal Entry form, enter the affected accounts, and record equal totals in the Debit and Credit columns. Add a clear memo, review the date and accounts, then save only after the entry balances.
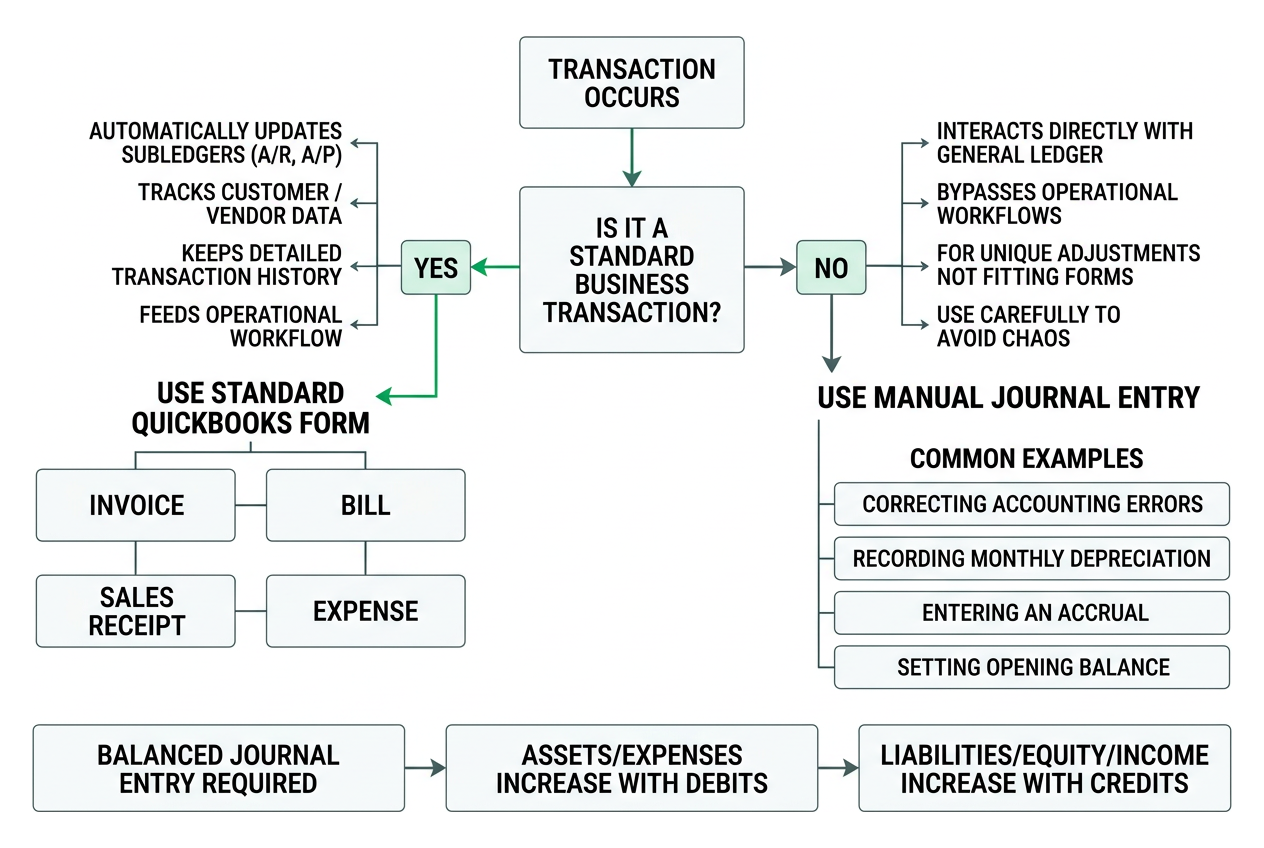
Use QuickBooks journal entries for manual adjustments that do not fit normal forms such as invoices, bills, sales receipts, or expenses. Common examples include correcting a transaction posted to the wrong account, recording monthly depreciation, entering an accrual, or setting an opening balance.
A journal entry changes the general ledger directly, so it is powerful but easy to misuse. Before posting one, make sure you understand this basic rule:
- Assets and expenses usually increase with debits.
- Liabilities, equity, and income usually increase with credits.
- Total debits must always equal total credits.
Good journal entries also leave a useful audit trail. Include a short memo that explains why the adjustment was made, and review the related account balances or reports afterward.
I am Charlie Perrin, founder of Cloud Bookkeeping, with more than 24 years of experience helping small business owners make sense of their financial records. I help clients use QuickBooks journal entries carefully, so their books are accurate, clear, and useful for better business decisions.
Discover more about QuickBooks journal entries:
When and Why to Use QuickBooks Journal Entries
At Cloud Bookkeeping, we often see small business owners treat the general journal as a catch-all tool whenever numbers look off. While it is one of the most flexible tools in your accounting software, it is also the easiest place to create unintentional chaos.
A general journal entry allows you to interact directly with your chart of accounts without creating standard source documents like customer invoices, vendor bills, or check payments. We rely on foundational accounting principles to keep financial statements clean and compliant. In double-entry bookkeeping, every financial event affects at least two accounts: one receives a debit, and the other receives an offsetting credit.
When you make manual adjustments, you bypass the normal operational workflows that feed your balance sheet and income statement. As highlighted in our guide to using QuickBooks for bookkeeping, understanding how data flows into your general ledger ensures your books remain reliable for tax season, lenders, and daily management decisions.
Standard Business Transactions vs. Manual Adjustments
QuickBooks is designed around source documents. When you make a sale, you should record an invoice or a sales receipt. When you incur an operating cost, you enter a bill or an expense. These standard forms do heavy lifting behind the scenes: they automatically update your Accounts Receivable (A/R) or Accounts Payable (A/P) subledgers, adjust inventory counts, apply correct sales tax rates, and organize reporting by customer or vendor.
Using a manual entry for everyday transactions strips out that valuable metadata. For instance, if you record customer payments or processor settlements using manual debits and credits instead of standard sales receipts, you lose the detailed tracking of individual line items, customer names, and product sales.
Save manual journal entries for end-of-period adjustments, non-cash transactions, and corrections that standard forms cannot handle.
Common Use Cases: Depreciation, Opening Balances, and Accruals
There are several legitimate scenarios where manual entries are necessary:
- Fixed Asset Depreciation: Spreading the cost of business vehicles, machinery, or office equipment over time. A monthly or annual entry debits Depreciation Expense and credits Accumulated Depreciation.
- Loan Amortization Splitting: When you make a regular loan payment, the principal reduces your liability, while the interest is an expense. If the initial bank feed transaction records the full amount to the liability, an adjusting entry moves the interest portion to the proper expense account.
- Accrual Accounting Adjustments: Recording revenues earned or expenses incurred before cash changes hands, such as accrued payroll or prepaid insurance amortization.
- Error Corrections and Reclassifications: Moving an expense mistakenly categorized under Office Supplies to Software Subscriptions.
- Setting Opening Balances: When establishing a new account or onboarding historical balances, entering opening balances in QuickBooks via the general journal connects the starting balance directly with Opening Balance Equity.
Step-by-Step Guide to Recording Journal Entries in QuickBooks
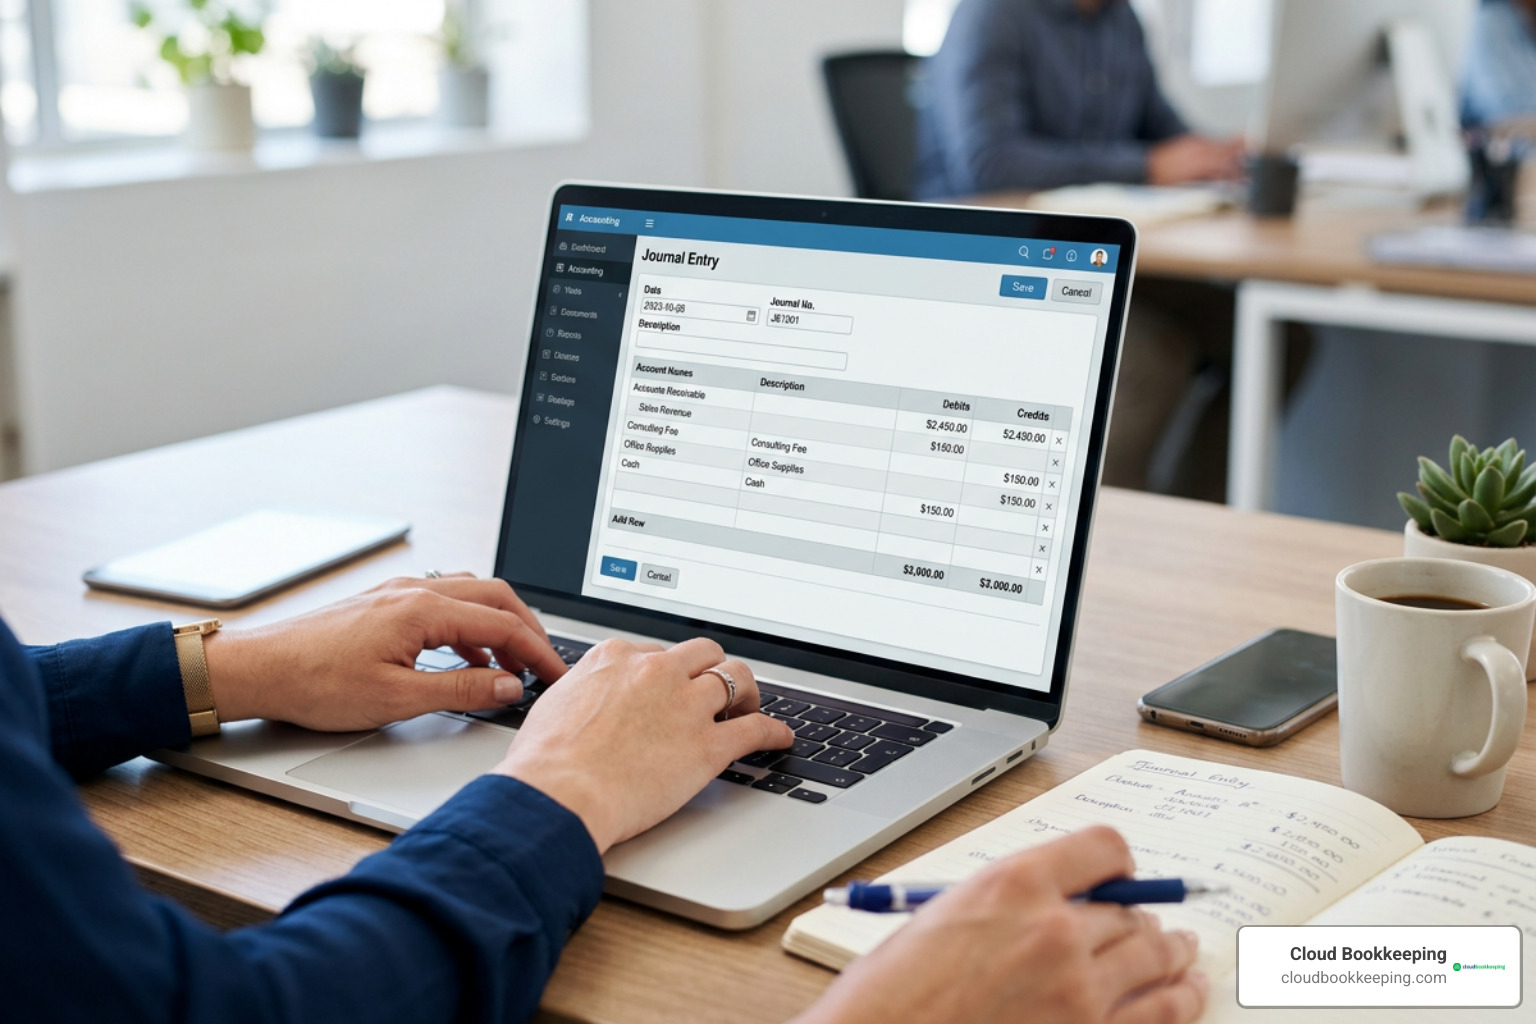
Recording an entry accurately requires attention to detail. Before opening the screen, gather your source documentation, determine the exact date of the adjustment, and identify which accounts are moving up or down.
How to Create QuickBooks Journal Entries in QuickBooks Online
Creating an entry in the cloud interface takes just a few clicks. Follow these exact steps to create journal entries in QuickBooks Online:
- Click the + New button in the upper left navigation menu.
- Under the Other column, select Journal entry.
- Set the Journal date. For period-end adjustments, ensure this matches the final day of the reporting period (such as December 31 for year-end books).
- Optionally enter a Journal no. to track the entry in your records.
- On the first line, select the target account from the Account dropdown.
- Enter the amount in either the Debits or Credits column.
- Add a descriptive Description (memo) explaining the exact purpose of this line item.
- If the line affects Accounts Receivable or Accounts Payable, select the specific customer or vendor in the Name column.
- On the second line, choose the corresponding offsetting account. Enter the equal balancing amount in the opposing column.
- Verify that the bottom totals match: Total Debits = Total Credits.
- Select Save and new or Save and close.
For business owners managing complex books, our approach to QuickBooks bookkeeping for small businesses ensures that every manual entry is thoroughly documented so you never have to guess why an adjustment was made months down the road.
Creating Journal Entries in QuickBooks Desktop for Windows and Mac
For companies using QuickBooks Desktop (Enterprise, Premier, or Pro on Windows or Mac):
- Go to the top menu bar and select Company.
- Choose Make General Journal Entries.
- Adjust the Date field to match the transaction date.
- Enter an identifying reference in the Entry No. field.
- In the distribution table, select your first account under the Account column.
- Input the appropriate figure into the Debit or Credit column.
- Type a clear explanation in the Memo column.
- Assign a Name if an entity is tied to the line, and select a Class if class tracking is enabled in your company preferences.
- Move to the next row and input the balancing entry.
- Look at the bottom right corner of the window. Ensure the Remaining balance reads $0.00.
- Click Save & Close to post the transaction to your general ledger.
Balancing Debits and Credits and Handling Multi-Currency Transactions
Understanding the mechanics of double-entry accounting removes the trial-and-error guesswork when building manual entries.
| Account Type | How to Increase Balance | How to Decrease Balance | Normal Balance |
|---|---|---|---|
| Assets (Bank, AR, Equipment) | Debit | Credit | Debit |
| Liabilities (AP, Credit Cards, Loans) | Credit | Debit | Credit |
| Equity (Owner’s Equity, Retained Earnings) | Credit | Debit | Credit |
| Income / Revenue (Sales, Service Fees) | Credit | Debit | Credit |
| Expenses (Rent, Payroll, Supplies) | Debit | Credit | Debit |
When working with multi-currency company files, journal entries require careful handling. If you operate accounts denominated in foreign currencies, QuickBooks prompts you for the currency reference and the exchange rate active on the transaction date.
That standard home-currency adjustments ignore foreign currency exchange fields because they adjust ledger values directly in your primary base currency. Always ensure exchange rates reflect actual market rates or realized figures from your bank statements to prevent currency gain/loss calculation errors during month-end closing.
Managing, Reversing, and Reporting on Existing Entries
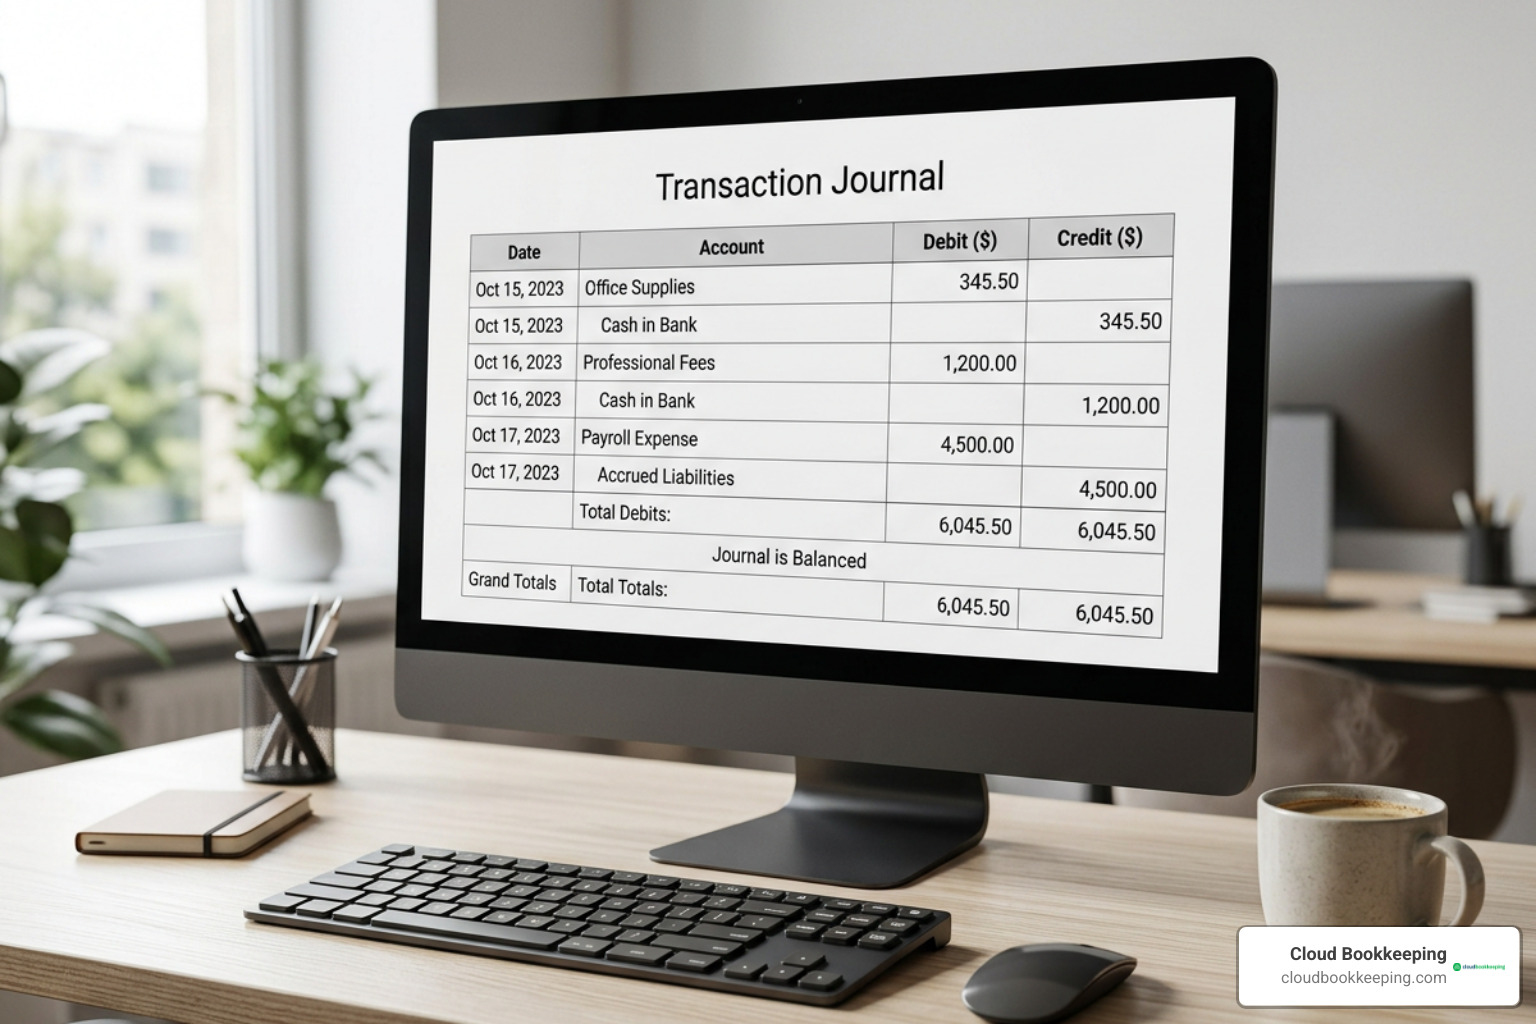
Once an entry is saved, it is not permanently locked in stone. You can review, modify, reverse, or delete historical entries to keep your books pristine.
Editing, Deleting, and Auto-Reversing Journal Entries
If you discover an error on a saved entry:
- Editing: Locate the transaction using search, the account register, or an audit report. Open the entry, modify the amounts, dates, or accounts, and select Save.
- Deleting: Open the transaction, select More at the bottom of the screen (or Edit in Desktop), and choose Delete. Confirm the prompt. Be careful: deleting removes the record entirely from the ledger. If you are audited, an unexplained deletion can raise flags.
- Reversing Entries: When recording month-end accruals that you expect to clear in the subsequent period (like accrued unbilled expenses), use the Reverse option. In QuickBooks Desktop, checking the Reverse box automatically creates an identical, opposing transaction dated the first day of the following month (marked with an “R” in the register). In QuickBooks Online, you can open the entry and select Reverse to generate the offsetting entry automatically.
Proper transaction maintenance plays a massive role in routine account balancing. Our QuickBooks reconciliation services help business owners catch duplicate entries, broken reversals, and mismatched balances before they impact tax returns or investor reports.
How to Run and Print a Transaction Journal Report
Reviewing your manual entries in a consolidated format helps verify that debits and credits were applied correctly across your entire business:
- Navigate to the Reports menu.
- In the search bar, type Journal and select the report.
- Set your desired Report period (e.g., This Month, Last Quarter, or Custom Dates).
- Click Customize or use the Filter settings to isolate Transaction Type = Journal Entry.
- Reorder or display columns such as Account, Debit, Credit, Memo, and Name.
- Click the Print icon to generate a physical copy or select Export to download a clean PDF or Excel spreadsheet for your CPA.
Advanced Adjustments and SDK Modifications for QuickBooks Journal Entries
For software developers, technical bookkeepers, and IT administrators integrating third-party software with QuickBooks Desktop, entries can be managed programmatically via the QuickBooks SDK.
When updating records through the API, you work with the JournalEntryMod object. Technical requirements to keep in mind include:
- TxnID and EditSequence: Every transaction has a unique system
TxnID. To update an entry, you must supply the currentEditSequence. This prevents concurrency errors and ensures changes are applied only to the most up-to-date version of the record. - TxnLineID Management: When editing individual lines in a journal entry, passing the existing
TxnLineIDupdates that specific line. Passing aTxnLineIDof-1instructs the API to append a brand-new line to the existing entry. - Currency Elements: If updating home currency values, the SDK ignores
IsAmountsEnteredInHomeCurrency,CurrencyRef, andExchangeRateelements, as adjustments are posted directly to base ledger amounts.
Developers can consult Intuit’s official JournalEntryMod technical reference for complete XML schema definitions and response status codes.
Frequently Asked Questions About QuickBooks Journal Entries
Why won’t QuickBooks let me save an unbalanced journal entry?
QuickBooks enforces fundamental double-entry bookkeeping rules. Every transaction must have equal total debits and total credits. If total debits exceed credits (or vice versa) by even one cent, the software disables the save button or displays an out-of-balance error message.
To resolve this, verify each line item’s math and ensure the difference between your debits and credits is exactly zero.
How do I correct a missing opening balance with a journal entry?
If you created a bank or liability account and forgot to set the beginning balance, you can fix it without starting over:
- Review your historical bank statement to identify the ending balance on the day prior to your QuickBooks start date.
- Create a new Journal Entry dated on or before that starting date.
- For an asset account (like Checking), enter the starting balance in the Debit column.
- On the second line, select Opening Balance Equity and enter the matching amount in the Credit column.
- Save the entry, open the account register, and mark the transaction as reconciled (“R”) to align your beginning balance for future reconciliations.
Why do Accounts Receivable and Accounts Payable lines require a name?
Accounts Receivable and Accounts Payable are balance sheet control accounts. Their balances must strictly equal the sum of all individual customer and vendor subledgers.
If you post a manual debit or credit directly to A/R or A/P without selecting a customer or vendor name, QuickBooks cannot assign the balance change to a specific party. This breaks subledger reports like the A/R Aging Summary or A/P Aging Detail. Selecting the entity name preserves subledger integrity.
Conclusion
Manual journal entries are an essential tool for maintaining balanced books, booking non-cash adjustments, and correcting account classifications. However, because they bypass standard documentation checks, using them correctly requires a solid grasp of debits, credits, and accounting principles.
At Cloud Bookkeeping, based right here in San Antonio, Texas, our team, led by Charlie Perrin, is dedicated to providing small business owners with crystal-clear reporting, responsive communication, and unmatched bookkeeping expertise. Whether you need help untangling past adjustments or want seamless monthly support, explore our professional bookkeeping and advisory services to keep your business finances organized, compliant, and positioned for sustainable growth.